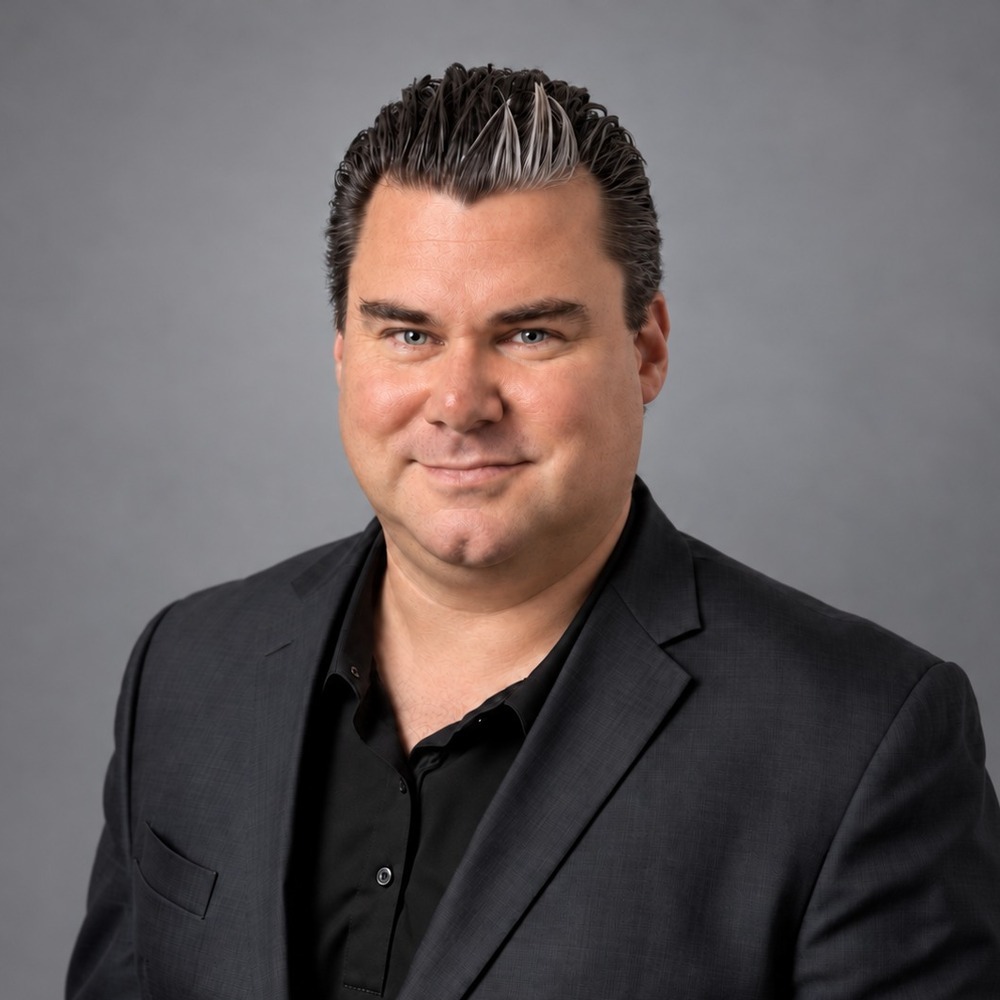
Scott Maidel is the Head of Institutional Solutions at Kai Asset Management and a Portfolio Manager for the Kai Convex solutions. Scott previously served as a Partner, Portfolio Manager, and Head of Hedge Funds Business at QVR, a quantitative derivatives and volatility trading firm offering solutions in hedged equity, multi-strategy absolute return, and derivative overlays. He was also previously Senior Portfolio Manager, Equity Derivatives at Russell Investments, where he was lead PM on a '40 Act call-overwriting mutual fund and subject matter expert for the firm in options and volatility, publishing numerous papers and conducting extensive consulting and large-scale overlay implementation for institutional clients. Scott previously served as Associate Director, Global Trading and Trade Research at First Quadrant and as Director of Institutional Solutions at Gladius Capital Management. Scott has over 20 years of trading and portfolio management experience with global derivatives.
Scott holds a B.Sc. in Investments and Financial Markets from the University of Southern California, an MBA from Pepperdine University, and is a Harvard Business School alumnus of the Program for Leadership Development (PLD). Scott is a CFA charter holder and Financial Risk Manager (FRM) certified.
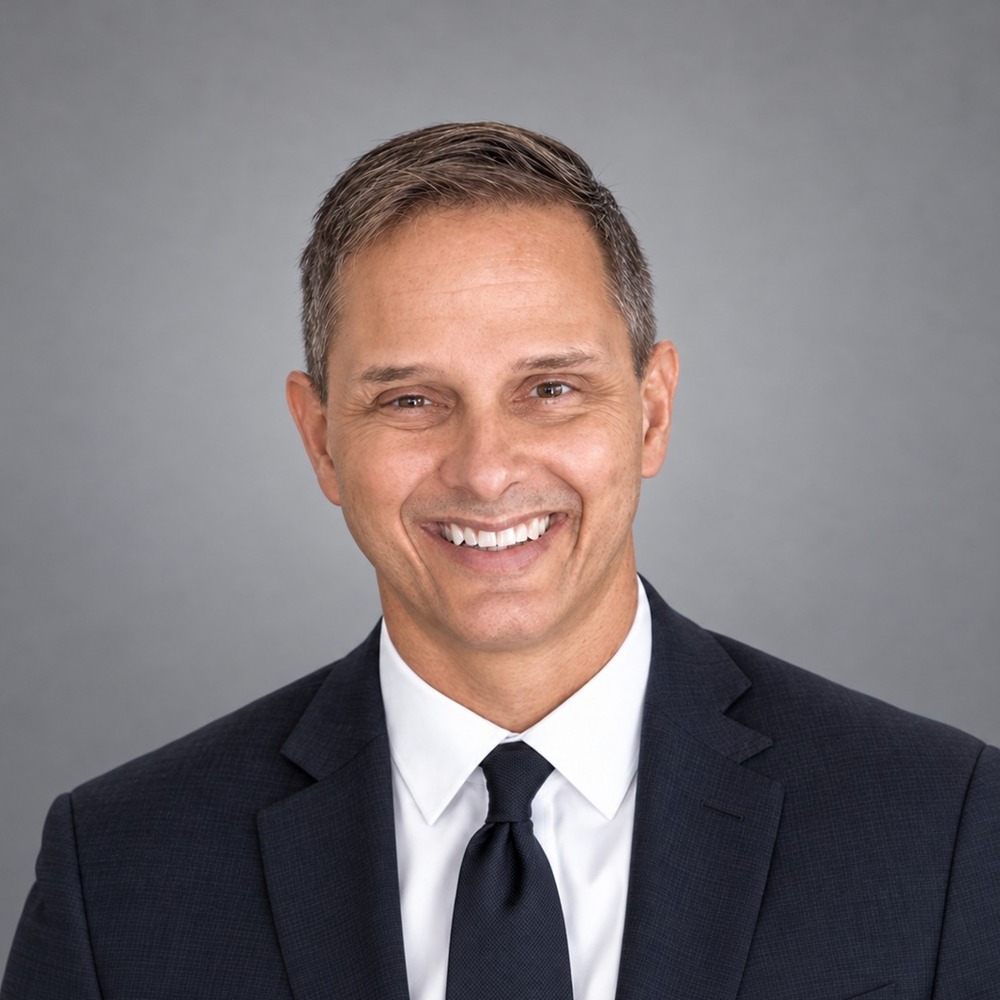
Noel Smith is the co-CIO and Head of Portfolio Management at Kai Asset Management/Kai Convex. Noel is also the Head of Options Trading at Tanius Technology. Noel previously served as Managing Partner and Chief Investment Officer of Convex Asset Management. As a member of the CME, CBOT, and CBOE, Noel has over 25 years of experience trading volatility, market-making, and managing risk. Noel is a frequent public speaker and guest on financial media. He collaborates with faculty and students at Columbia University, has authored white papers, and speaks at many industry conferences. Noel was CIO and Portfolio Manager at two Chicago-based proprietary derivatives trading firms. He was the seed investor who financed the launch of GETCO LLC (KCG/Virtu), a global high-frequency trading firm that grew to account for 20%+ of U.S. trading volume. As a founding member of Third Millennium Trading in 1996, Noel led the firm to become one of the largest U.S. equity options market makers, backing over 65 traders at the CBOE, CME, and CBOT.
Noel attended the University of Illinois at Urbana-Champaign, where he received a degree in Biochemistry and performed research at the Beckman Institute in Neuroscience. As a student, Noel played on the University of Illinois men's ice hockey team. Noel is a proud veteran of the U.S. Army, where he was a specialist in microwave and satellite communication systems.